When you sell on your own, every way of getting paid has a price. The fee on the screen is only part of it. The real cost is the fee, plus the time until the money is actually available, plus the odds of never collecting at all. Here are the verified numbers, with sources.
What the three most-used processors charge today
Stripe charges 2.9% + 30¢ for online payments and 2.7% + 5¢ when you tap or swipe a card in person. Square charges 2.6% + 15¢ in person and 3.3% + 30¢ online on its free plan. PayPal Checkout charges 3.49% + 49¢, or 2.99% + 49¢ for a plain card payment.
- Stripe rates: stripe.com/pricing, retrieved August 27, 2026
- Square rates: squareup.com/us/en/pricing, retrieved August 27, 2026
- PayPal rates: paypal.com, effective July 15, 2026
What you keep from a $100 invoice
- Stripe in person: you pay $2.75, you keep $97.25
- Square in person: you pay $2.75, you keep $97.25
- Stripe online: you pay $3.20, you keep $96.80
- PayPal, standard card: you pay $3.48, you keep $96.52
- Square online, free plan: you pay $3.60, you keep $96.40
- PayPal Checkout: you pay $3.98, you keep $96.02
The gap between the most expensive and the cheapest card option on that list is $1.23 per $100. That sounds trivial. Across a hundred invoices it is $123, and across a thousand it is $1,230 — money that leaves your pocket without ever showing up in your books, because it never arrived.
Bank transfer is the cheapest, and almost nobody offers it
Stripe charges 0.8% for ACH Direct Debit, capped at $5. The cap is the part that matters: above $625 you pay a flat five dollars, no matter how large the invoice. Square charges 1% on invoices paid by bank transfer, with a $1 minimum and a $10 cap on its paid plans.
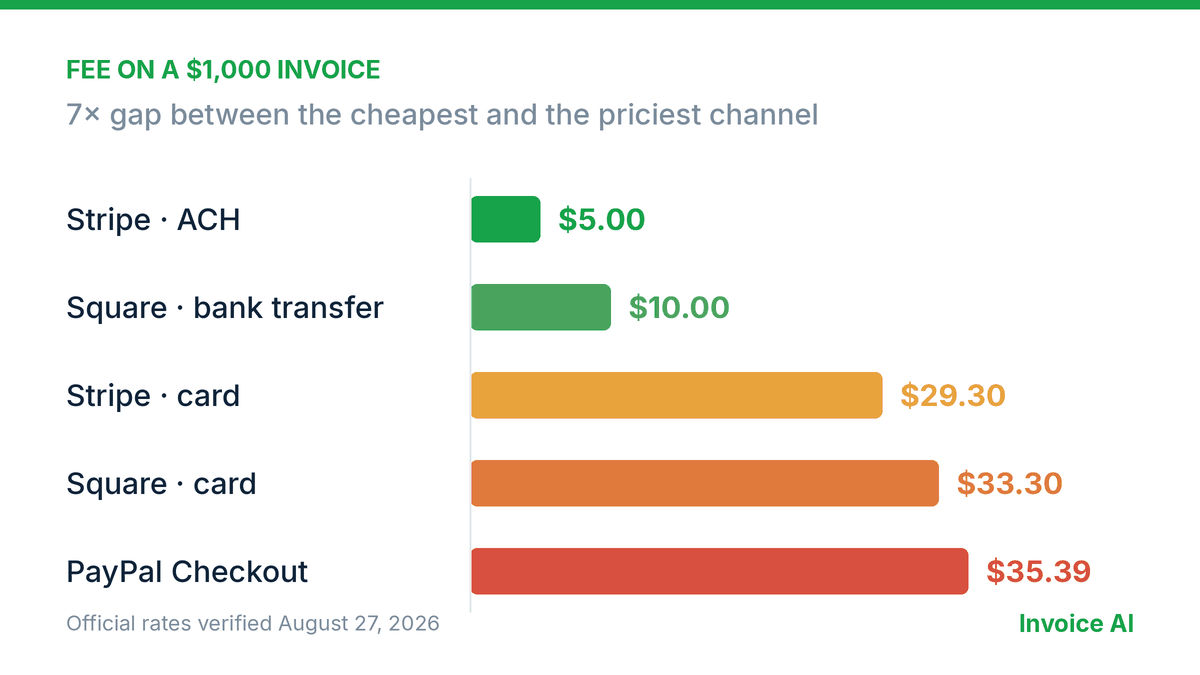
The same invoice, at $1,000
- Stripe ACH Direct Debit: you pay $5.00, you keep $995.00
- Square invoice by bank transfer: you pay $10.00, you keep $990.00
- Stripe online card: you pay $29.30, you keep $970.70
- Square online, free plan: you pay $33.30, you keep $966.70
- PayPal Checkout: you pay $35.39, you keep $964.61
That is a $30.39 difference between PayPal Checkout and Stripe ACH on a single thousand-dollar invoice. If you collect $10,000 a month by card when you could collect it by bank transfer, you are paying roughly $300 every month for the convenience of not asking.
If your client is outside the United States
Stripe adds 1.5% when the card is international, plus 1% more if currency conversion is required. PayPal adds 1.50% for cross-border transactions, and its conversion spread reaches 3% or 4% depending on the case. On a $1,000 invoice, the fee can climb from $35 to nearly $90.
Zelle looks free. Its cost sits somewhere else.
Zelle charges no fee, and Chase confirms it adds no charges of its own. But Zelle warns on its own small-business page that a payment cannot be cancelled once it is sent to someone already enrolled, and that it offers no protection for goods-and-services purchases.
Your bank sets the limits, not Zelle, and they are not always published. Chase determines each transaction's limit at the moment you set it up, based on several factors. For a large invoice, that means you do not know whether it will go through until your client tries and calls to say it did not.
One detail that surprises people: Zelle does not report payments made on its network to the IRS, not even payments for the sale of goods and services. That does not exempt you from reporting them. It just means the record is yours to keep. Source: zelle.com, retrieved August 27, 2026.
Cash is not free either
Cash is still very much alive. According to the Federal Reserve's Diary of Consumer Payment Choice, published May 11, 2026, consumers pay with cash for roughly 1 in 7 payments, 4 out of 5 used cash in the last 30 days, and 90% plan to keep using it.
Its cost never appears on a statement. It is the trip to the bank, the drawer that does not balance at closing, the bill nobody can account for, and above all the sale that gets recorded nowhere. When tax season arrives, that invisible sale is the expensive one. Source: Federal Reserve Financial Services.
The cost that swallows all the others
A 3.49% fee on a $1,000 invoice is $34.90. A $1,000 invoice that is never collected is $1,000. Any channel that gets you paid faster and with less friction is worth far more than the three dollars you save by picking the cheapest processor on the list.
So the right question is not which one charges least. It is which one gets your client to pay today. If the card is in their hand and the link is one tap away, they pay. If they have to remember a bank transfer tomorrow, tomorrow it slips, and you are calling next week.
Can you pass the fee to the customer in Florida?
Florida had a law banning surcharges for card payments. The Eleventh Circuit Court of Appeals struck it down as unconstitutional on November 4, 2015, in Dana's Railroad Supply v. Attorney General, holding that it was an impermissible restriction on free speech.
Legal does not mean automatic. Visa requires you to notify your acquirer 30 days before you start surcharging, and to disclose it to customers with visible signage. Debit rules are different. Confirm with your processor and a lawyer first — this is information, not legal advice.
The practical rule
- Under $50, in person: card or cash. The fixed per-transaction cost is what dominates, not the percentage.
- Invoices above $600: offer bank transfer before card. That is where the $5 cap changes the outcome entirely.
- Clients abroad: check the cross-border and conversion charges before accepting. They can double your fee.
- Zelle: use it with clients you already know and who have paid you before. Never with a new one.
- Whatever the channel: send the invoice the same day. The delay costs more than any fee on this list.
None of these numbers are permanent. All were verified on August 27, 2026 on the official pages linked above. Processors change their rates with advance notice, and it is worth revisiting them once a year, with a calculator and your own volumes in front of you.
At Invoice AI we work with one-person businesses. What we see over and over is not that they pick the wrong processor. It is that the invoice goes out three days late.