A returned invoice does not cost you paperwork. It costs you a month. The client is not disputing the amount or the work — the document simply fails to clear their internal process, lands back in your inbox, and the payment clock starts over from zero. The worst part is that it is almost always one missing detail that would have fit on a single line.
The good news: you do not have to guess which detail. Official, published lists exist that define what turns a document into a valid invoice. They are useful even when your client is the hardware store down the street.
What "complete invoice" actually means
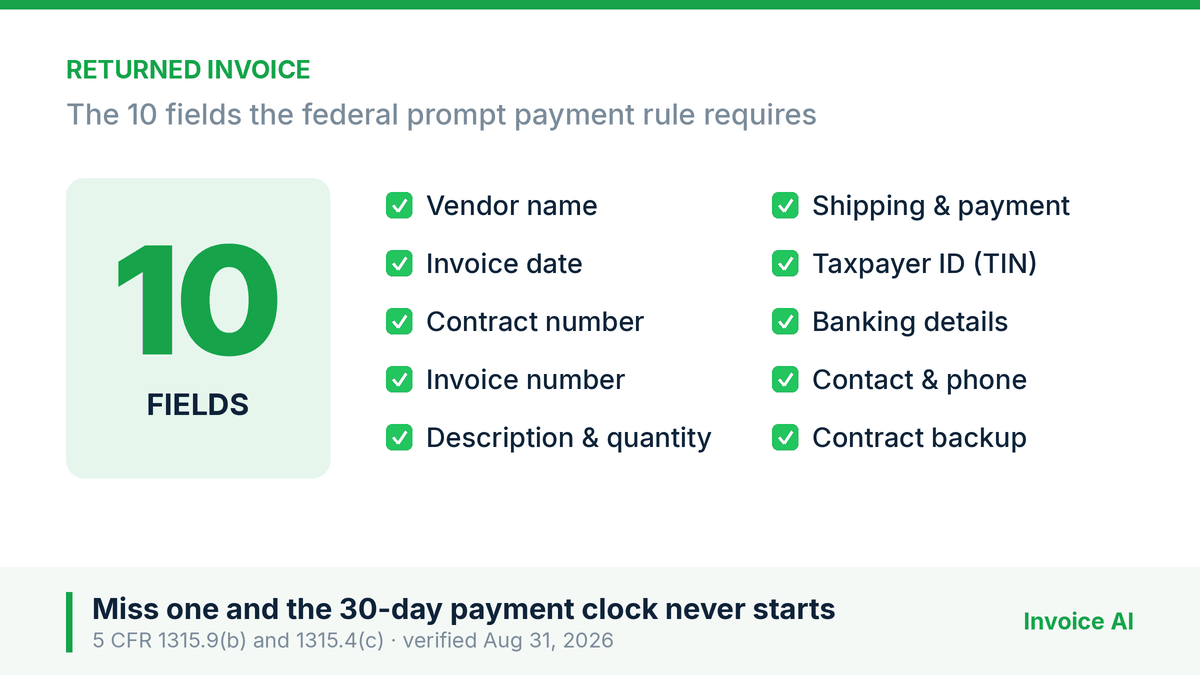
An invoice gets returned when it is missing something the client needs in order to approve it internally. No annoyed person rejects it — a procedure stops it. In the U.S. federal government that list is written down, and it has ten items. If a single one is missing, the invoice does not count as received.
The list lives in 5 CFR 1315.9(b), the prompt payment rule that binds federal agencies. Checked on August 31, 2026, it requires:
- Name of vendor
- Invoice date
- Government contract number, or other authorization for delivery of goods or services
- Vendor invoice number, account number, or any other agreed identifying number
- Description, price and quantity of the goods and services rendered
- Shipping and payment terms
- Taxpayer Identifying Number (TIN)
- Banking information for the deposit
- Contact name, title and telephone number
- Any other substantiating documentation the contract requires
Read it again with your last late payment in mind. What is usually missing is the third item — the reference that lets the client tell which purchase your invoice belongs to — or the ninth, a phone number for someone to ask.
The clock does not start until the invoice is complete
This is the part that changes how you look at the problem. Under 5 CFR 1315.4, the agency must return a defective invoice "as soon as practicable after receipt, but no later than 7 days after receipt" (paragraph c). The standard payment period, if the contract says nothing else, is 30 days from receipt of a proper invoice (paragraph g).
In other words: sending an incomplete invoice does not put you further back in the line. It takes you out of the line. And when you fix it, the 30-day count begins on the day the good version arrives, not the day you sent the first one.
The cost of that delay has a published price. The U.S. Treasury sets the prompt payment interest rate at 4.75% for the period July 1 through December 31, 2026. That is what the government charges itself for being late. Your private client pays you nothing for the same delay, unless you wrote it into the agreement.
Florida wrote the other half of the rule
Florida law requires local governments to explain why they send something back. Under Fla. Stat. 218.735(2), for construction services the entity must reject the invoice within 20 business days after the date it was stamped as received, and "the rejection must be written and must specify the deficiency and the action necessary to make the payment request or invoice proper."
That sentence is a template for what you should ask of any client who bounces something back: in writing, what is missing, and what needs to happen. Once corrected, the same statute allows 10 business days to pay or reject again (218.735(3)).
For purchases other than construction, Fla. Stat. 218.74(2) sets the due date at 45 days, and subsection (4) applies interest of 1 percent per month on the unpaid balance when payment does not arrive within 30 days after that due date.
Tax goes on its own line, and that part is mandatory
In Florida, sales tax does not dissolve into the price. Fla. Stat. 212.07(2) states that a dealer shall add the tax to the sale price and that "the amount of the tax shall be separately stated as Florida tax on any charge ticket, sales slip, invoice, or other tangible evidence of sale."
The same section, at (4)(a), prohibits advertising that you will absorb the tax or that it will not be added to the selling price. An invoice with the tax buried inside the total does not just look sloppy — it works against the statute behind it. This is general information, not tax advice; for your own situation, talk to your accountant.
What the IRS wants to see afterward
An invoice does not end its life when you get paid. IRS Publication 583 asks you to keep supporting documents that "show the amounts and sources of your gross receipts," and it names invoices among them, alongside cash register tapes, receipt books and credit card charge slips.
The IRS puts it plainly on its burden of proof page: "The responsibility to prove entries, deductions, and statements made on your tax returns is known as the burden of proof." Your invoice is that proof. If it lacks a description of what you sold, so do you.
The 60-second checklist, before you hit send
- A unique invoice number that does not repeat any earlier one
- An unambiguous date — "Sep 3, 2026" cannot be misread; "03/09/2026" can
- Your legal name, address and taxpayer identification number
- The client's exact name, spelled the way they spell it, not the way you saved it
- The reference they use: purchase order, contract or job number
- A description their approver can recognize without calling you
- Quantity and unit price on separate lines
- Tax on its own line, with the rate visible
- One clear total, with no surprises underneath it
- Payment terms and a calculated due date, not just "Net 30"
- How to pay you: bank, link or method, with complete details
- A name and a phone number for questions
The four mistakes that cause the most returns
The duplicate number leads the list, because the client's system reads it as a repeat and blocks it before a human ever sees it. Next comes the ambiguous date, which flips month and day for an international client. Third, the missing reference: with no purchase order, the invoice has nowhere to be filed. Fourth, the generic description — "services rendered" — which nobody can approve internally without asking again.
None of the four is a technical problem. All four take two minutes. And in a year when 77% of firms told the Federal Reserve that rising costs were their leading financial challenge (Small Business Credit Survey, published March 3, 2026), a month lost to one missing line is among the most expensive mistakes a one-person business can make.
This article is general information and does not constitute legal or tax advice. The rules cited apply to the cases they themselves describe; for your situation, consult a professional.