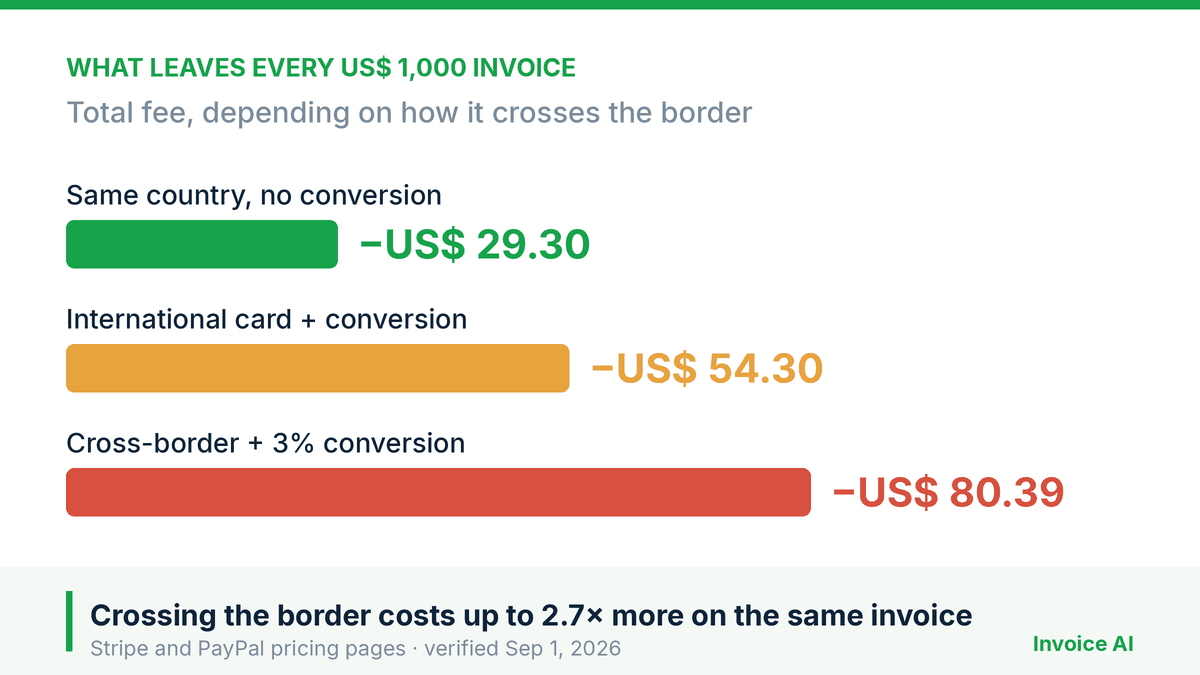
Invoicing another country rarely fails on price. It fails on what the invoice does not say. Between the processor's fee and the conversion margin, a US$ 1,000 invoice can arrive as US$ 919. And no central bank's official exchange rate obliges anyone to use it.
Line 1 — The currency, with its three-letter code
The "$" sign does not identify a currency. It is used by the US dollar, the Mexican, Colombian, Argentine, Chilean, Uruguayan and Dominican pesos, among others. An invoice that says "$1,500" and crosses a border is an ambiguous invoice, and ambiguity is always resolved in favor of whoever is paying.
That is what ISO 4217 is for: three-letter codes "for the representation of currencies that enable clarity and reduce errors." The first two letters come from the country, the third from the currency: USD, MXN, COP, BRL, DOP. Write USD 1,500.00, not "$1,500."
Put it in three places: next to the total, next to each line if more than one currency appears, and in the payment instructions. It costs three letters and avoids the most awkward conversation of the month.
Line 2 — The rate: which one, from what day, from whom
Almost every country publishes an official reference rate, and almost nobody knows that is all it is — a reference.
- Mexico — the FIX rate is set by the Banco de México from an average of wholesale market quotes, released "a partir de las 12:00 horas de todos los días hábiles bancarios" and published in the official gazette one business day later.
- Colombia — the TRM is calculated and certified by the financial regulator "con base en las operaciones registradas el día hábil anterior por los intermediarios del mercado cambiario," per the Banco de la República.
- Brazil — the Ptax is the average of four dealer surveys between 10 a.m. and 1 p.m.; in each one the two highest and two lowest quotes are discarded.
- Euro area — the ECB publishes its reference rates at around 16:00 CET, reflecting the market at 14:15 CET.
Here is the part almost nobody reads. On the TRM, the Banco de la República says: "No se trata de una tasa de cambio que deba aplicarse en forma obligatoria en los contratos" — it is not a rate that must be applied in contracts. The ECB is blunter still: its rates "are not intended to be used in any market transactions, whether directly or indirectly, but for information purposes only."
Translated: if your invoice does not say which rate you applied and from what date, no rate applies. The one that applies is your customer's bank or processor's, which is not the same one. The sentence you need is one line: "Converted to USD at the [central bank] reference rate of [date]."
Line 3 — Who pays for conversion and fees
This is the line that decides what you keep, and hardly any invoice carries it. Today's numbers, from the providers' own pricing pages:
Stripe charges 2.9% + US$ 0.30 per domestic card transaction, +1.5% for international cards and +1% when currency conversion is required. On a US$ 1,000 invoice with all three: 5.4% plus 30 cents, US$ 54.30. You keep US$ 945.70.
PayPal, on fees last updated July 15, 2026, charges 3.49% + US$ 0.49 for PayPal Checkout, +1.50% for cross-border transactions and a currency conversion spread of 3.00% over the base rate — 4.00% in some cases. On the same US$ 1,000: 7.99% plus 49 cents, US$ 80.39. You keep US$ 919.61.
US$ 26.09 of difference on a single invoice, same work, same client. On US$ 10,000 invoiced a month that is roughly US$ 260 a month that has nothing to do with selling more.
There is a third model worth knowing. Wise states it uses "the live mid-market rate, and a small, upfront fee" — the mid-market rate with no hidden markup, and the fee shown separately. It is not automatically cheaper on every corridor, but it is comparable, which a hidden markup never is.
Line 4 — What happens if the rate moves between invoice and payment
A 30-day invoice is an open position in a currency you do not control. Invoice in pesos and get paid in pesos, and nothing happens. Invoice in pesos while your costs are in dollars, and those 30 days of movement are yours to absorb.
There are three ways to close it, and all three are a line of text:
- Invoice in your cost currency. The risk moves to the client. Simplest, and the least popular on the other side.
- Fix the rate as of the issue date, written on the invoice. It locks the number, but a badly late payment still costs you the difference.
- Apply the rate on the payment date, and say so. It is the fairest, and it means the total is "approximate" until the money lands.
What does not work is saying nothing: then your customer's bank decides, and never in your favor.
The leg you never see
Between your customer's bank and yours there are usually intermediary banks, and each can deduct its fee from the amount in transit. That is how transfers arrive short without anyone lying.
For scale, the World Bank's figure helps: moving money across borders costs a global average of 6.36% of the amount sent — from its September 2025 report, and it measures personal remittances, not business invoices. It is not your exact cost; it is the order of magnitude of crossing a border with money.
The practical defense is two sentences in the payment instructions: which account and which currency you want to be paid in, and who absorbs intermediary bank fees. Say nothing and you absorb them.
What a well-built international invoice looks like
- The currency with its ISO 4217 code next to the total: USD 1,500.00.
- The rate applied, its source and its date, if the invoice shows two currencies.
- A line stating who pays conversion and bank fees.
- Which rate governs if payment is late: issue date or payment date.
- The payment method you prefer, with what it costs both sides.
- Complete bank details, so nobody has to guess and come back asking.
None of those lines makes you more per hour. All of them keep you from losing 5% to 8% of every invoice for not having written them.
This is general information, not legal or tax advice. Processor fees and each country's currency rules change; confirm yours before invoicing.